Emergency Roof Repair Before the Insurance Adjuster Arrives
A useful guide to emergency roof repair before insurance adjuster should separate roof condition and contractor scope from policy interpretation, claim handling, and payment decisions controlled by the insurance company.
The search for emergency roof repair before insurance adjuster often begins after a storm, leak, inspection, failed patch, or recurring maintenance problem. A useful estimate should define the source, repair boundary, materials, access, hidden-condition process, and expected result.
A useful guide to emergency roof repair before insurance adjuster should separate roof condition and contractor scope from policy interpretation, claim handling, and payment decisions controlled by the insurance company. Any estimate should also state what happens if concealed moisture, rotten wood, incompatible materials, or a larger failure pattern is found after access is opened.
Quick answer
A useful guide to emergency roof repair before insurance adjuster should separate roof condition and contractor scope from policy interpretation, claim handling, and payment decisions controlled by the insurance company.
The safest next step is a documented inspection and itemized scope—not roof climbing or a blind surface patch.
What this condition usually means
The visible condition is evidence, not always the source. Water can move along decking, fasteners, framing, membranes, or trim before it appears inside. Wind can loosen a material without removing it. Drainage can fail at an outlet even when the gutter or roof surface looks clean.
This page supports the broader Homeowners Insurance and Roof Replacement resource and is designed to help homeowners ask better questions before approving work.
What homeowners may notice first
- Temporary repairs completed to prevent additional damage
- Requests for photographs, invoices, maintenance records, or proof of age
- A recent event followed by visible roof changes or interior damage
- Questions about deductibles, depreciation, matching, or scope
- An estimate that differs materially from the insurer’s initial document
One symptom does not prove one cause. Patterns, timing, weather, and connected components should be considered together.
Common causes and contributing conditions
A useful diagnosis distinguishes the initiating cause from the damage it created. For example, a loose component may be the result of failed fastening, while rotten wood below it may be the result of months of water entry. Both need to be addressed in the correct order.
- Material availability or matching issues
- Incomplete documentation of temporary and permanent work
- Different measurements or assumptions about affected roof sections
- Policy terms, exclusions, limits, and settlement methods
- Hidden conditions discovered after work begins
What a professional inspection should cover
Terra Nova begins with safe exterior and interior observations, then narrows the repair boundary. The inspection records what is confirmed, what is suspected, what cannot be seen without removal, and what would trigger a written change order.
- Step 1: Keep temporary-repair invoices and photographs
- Step 2: Compare insurer and contractor scopes line by line
- Step 3: Ask the insurer or licensed coverage professional to explain policy decisions
- Step 4: Read the policy and claim correspondence rather than relying on summaries
- Step 5: Document roof and interior conditions with dates
Condition, cause, and next-step table
| Observed condition | What it may indicate | Professional next step |
|---|---|---|
| A recent event followed by visible roof changes or interior damage | Policy terms, exclusions, limits, and settlement methods | Respond to requests with organized supporting records |
| Questions about deductibles, depreciation, matching, or scope | Hidden conditions discovered after work begins | Use written change orders for concealed conditions |
| An estimate that differs materially from the insurer’s initial document | Material availability or matching issues | Complete covered and homeowner-elected work under a clear contract |
| Temporary repairs completed to prevent additional damage | Incomplete documentation of temporary and permanent work | Escalate policy disputes through appropriate insurance or legal channels rather than the roofer |
Professional repair approaches
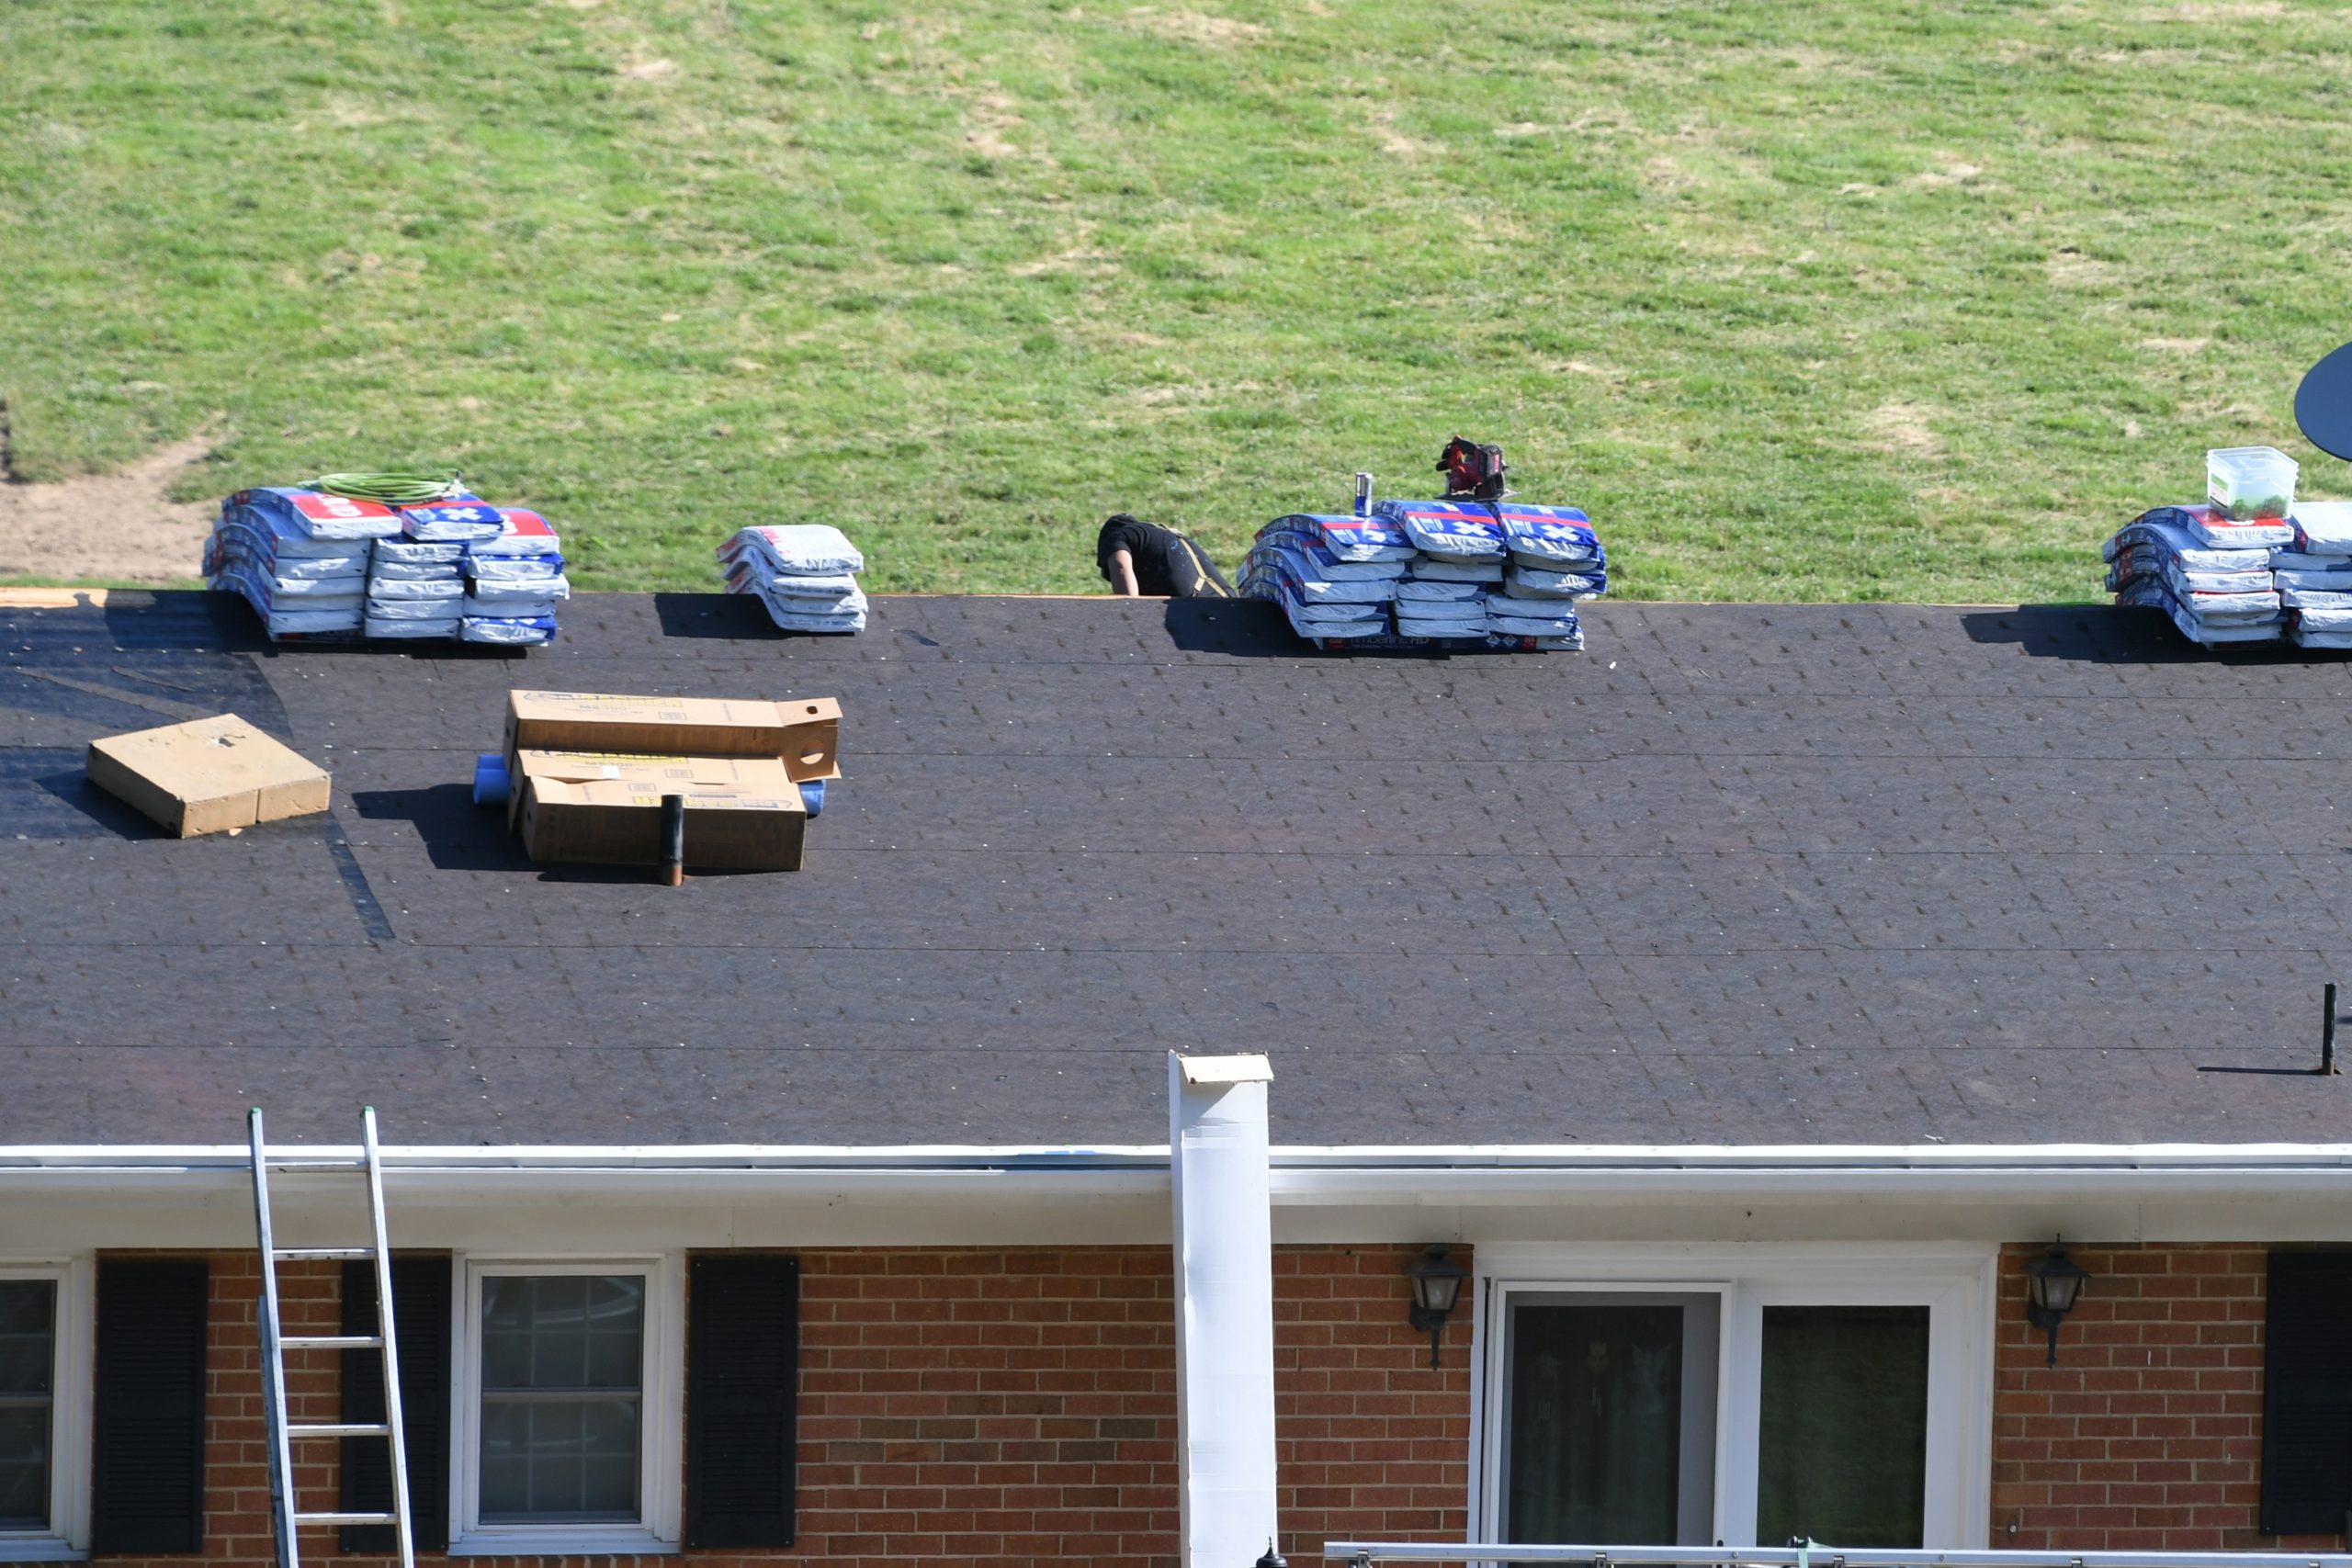
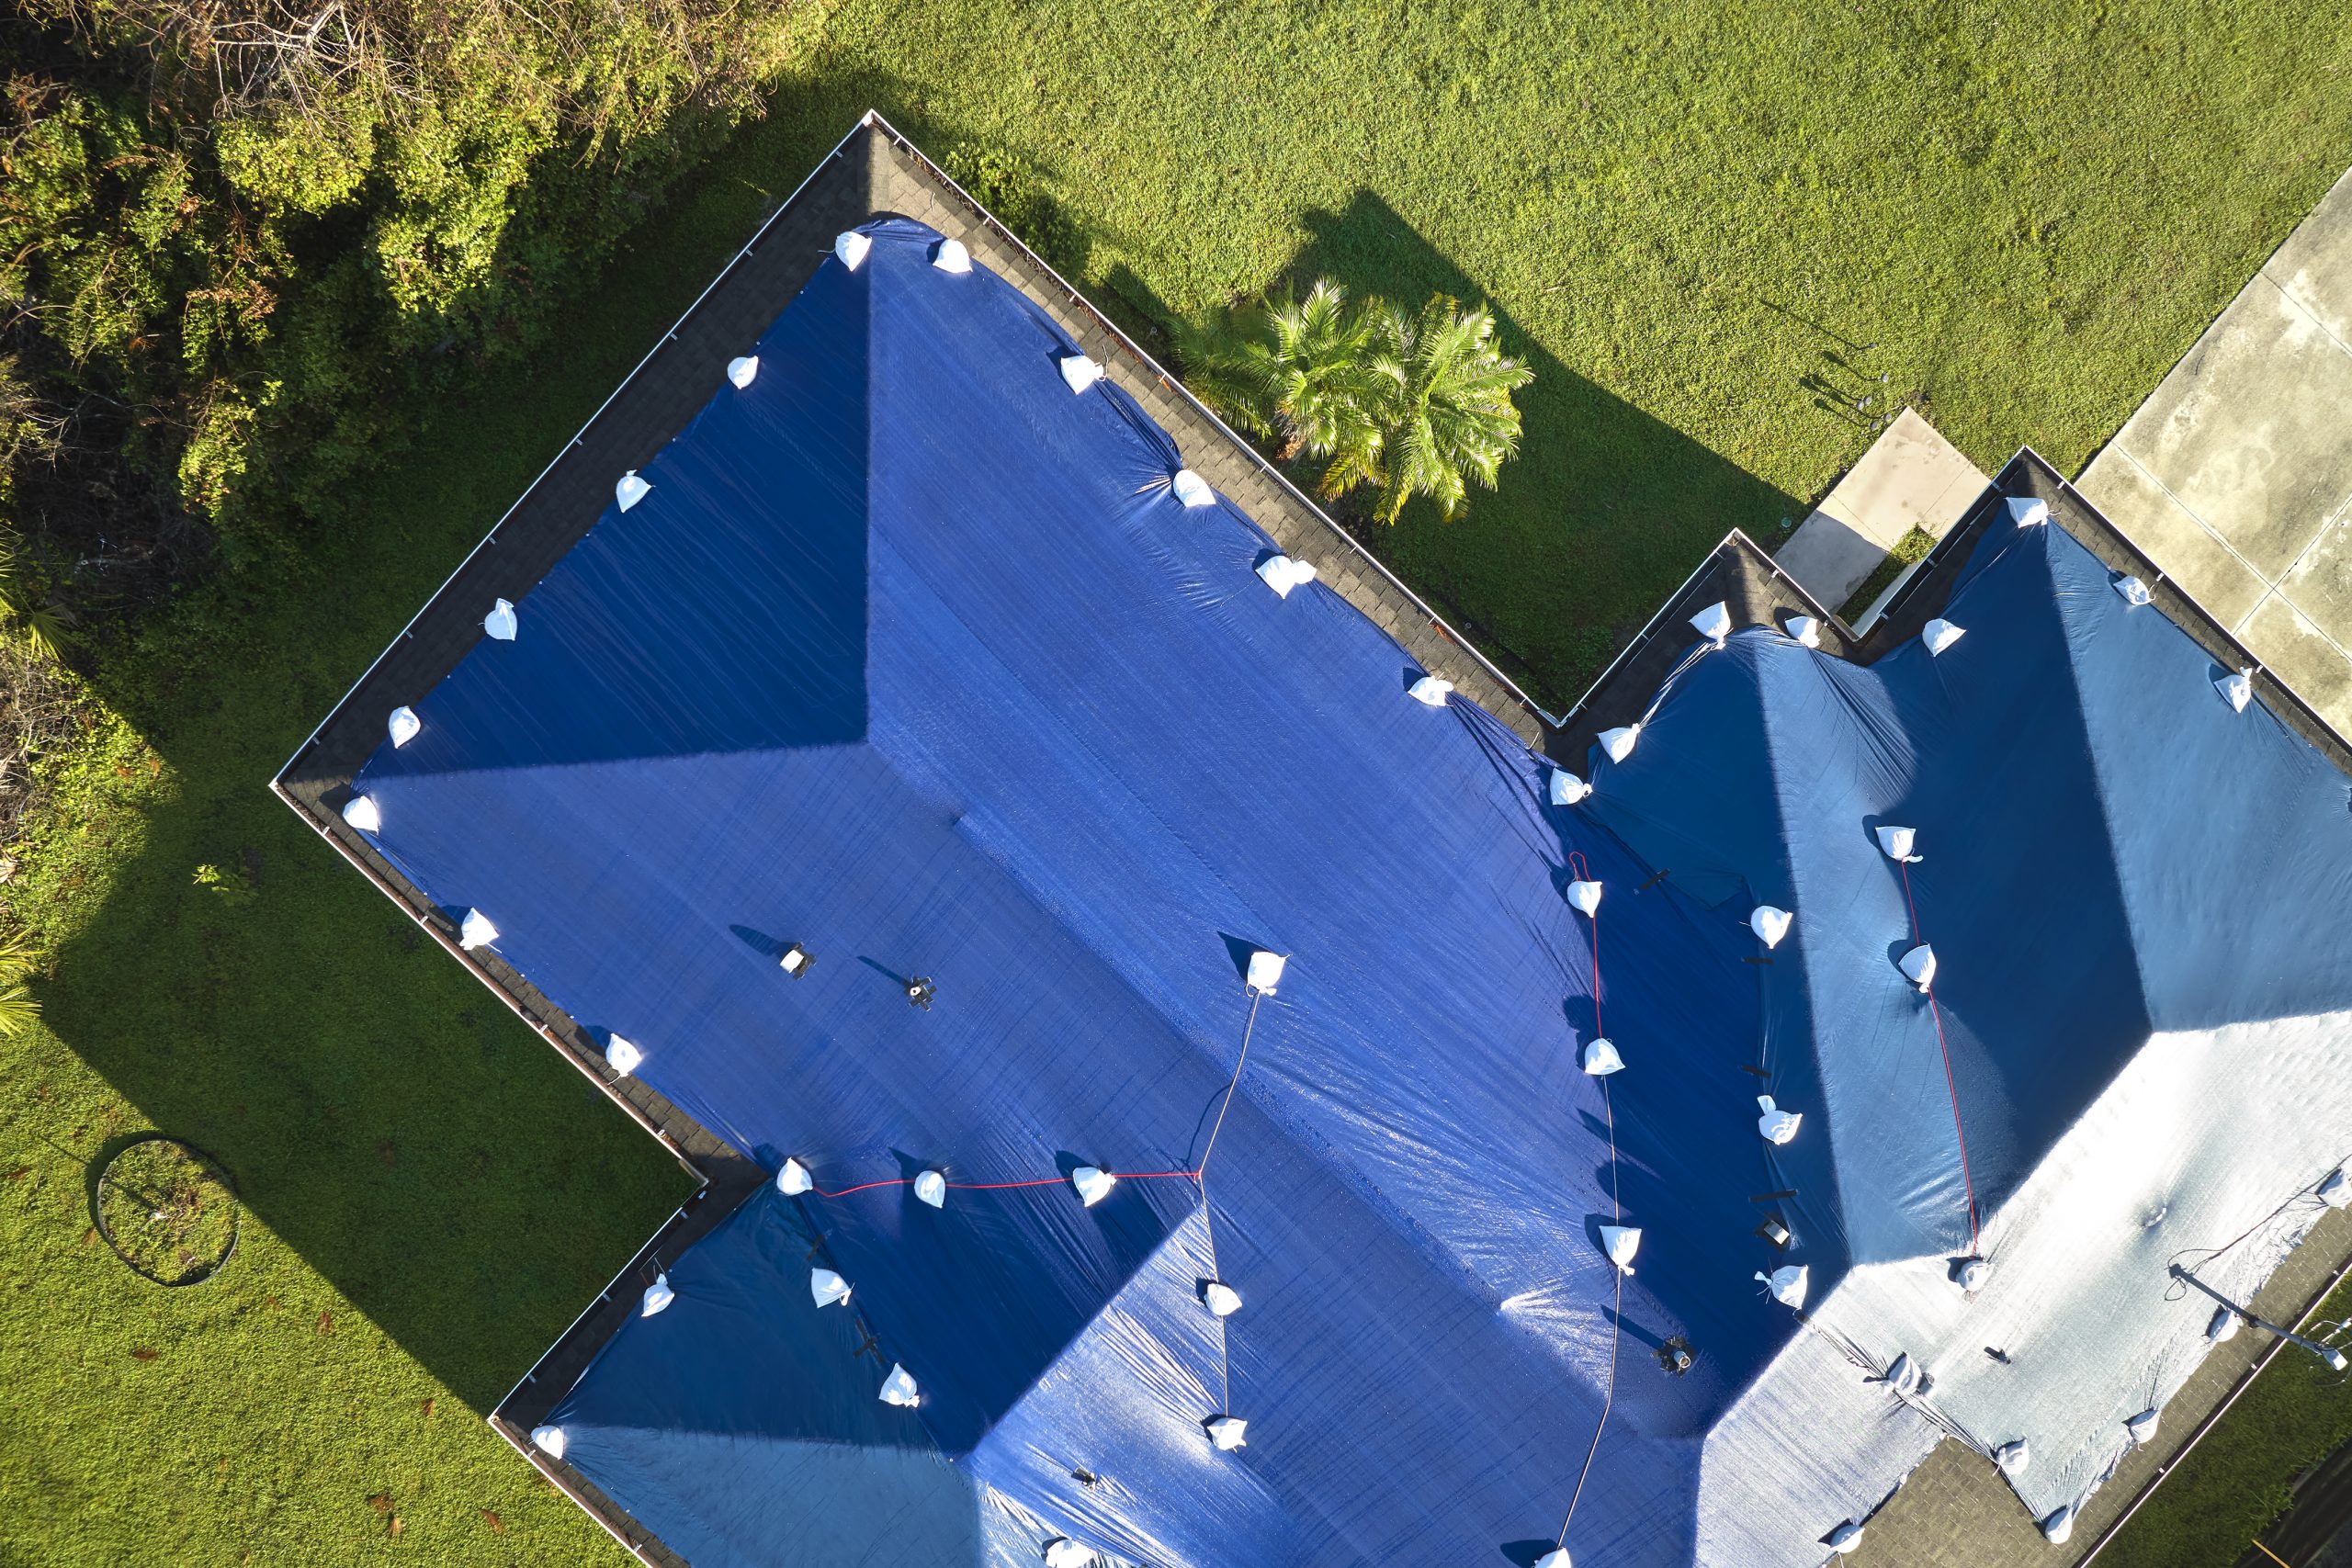
Temporary protection and permanent work should be named separately. Tarping, sealant, or emergency stabilization can reduce immediate exposure, but it should not be presented as the final repair unless the system is actually rebuilt to a durable standard.
- Complete covered and homeowner-elected work under a clear contract
- Escalate policy disputes through appropriate insurance or legal channels rather than the roofer
- Provide accurate contractor measurements and repair scope
- Respond to requests with organized supporting records
- Use written change orders for concealed conditions
What the written scope should identify
- Confirmed cause and repair boundary
- Materials and components to be removed or reused
- Known exclusions and concealed-condition process
- Temporary protection versus permanent work
- Cleanup, photographs, warranty, and final walkthrough
Records to keep
- Dated inspection photographs
- Itemized estimate and signed contract
- Product and color selections
- Written change orders with supporting photos
- Invoice, warranty, permit, and completion records
When a targeted repair is enough
The homeowner should compare the expected life of the repair with the cost and disruption of future mobilization. A low-cost patch may be sensible on a young roof with one defect, but poor value on an aging system with repeated leaks and multiple failing components.
For a broader decision framework, compare Roof Repair New Jersey with Roof Replacement New Jersey and use the actual condition of the property to choose the scope.
Budget factors homeowners should compare
A meaningful price cannot be reduced to one universal number. Height, pitch, system type, matching, safety setup, weather protection, and connected damage all matter. Comparing itemized scope protects the homeowner better than comparing totals alone.
- Difference between insurer pricing assumptions and actual contracted work
- Deductible and homeowner-selected upgrades
- Settlement method and release of depreciation
- Items included, excluded, or limited by the policy
- Emergency mitigation and temporary repairs
Common homeowner mistakes to avoid
- Failing to keep invoices for reasonable temporary protection
- Signing documents without understanding assignment or payment terms
- Treating every disagreement as proof of bad faith without reviewing the policy and evidence
- Assuming a contractor can promise claim approval
- Confusing the roofing estimate with a coverage decision
New Jersey weather and property considerations
Bergen, Passaic, Essex, Hudson, Morris, and Union County homes face wind-driven rain, snow, ice, summer heat, falling branches, and rapid freeze-thaw changes. These conditions make flashing, fastening, drainage, and compatible repair materials especially important.
Municipal permit or inspection requirements can vary with the location and scope. The contract should state who verifies applicable requirements and how concealed conditions or scope changes will be documented.
How the project should move from diagnosis to completion
- Step 1: Discuss the symptom, history, and urgency
- Step 2: Inspect and document the connected system
- Step 3: Explain repair, replacement, and monitoring options
- Step 4: Provide a written scope with clear assumptions
- Step 5: Complete the work, cleanup, photographs, and walkthrough
Original Terra Nova services and resources
- Homeowners Insurance and Roof Replacement
- How to Identify Roof Storm Damage
- What Hail Damage Looks Like on a Roof
- Roof Inspection in North Jersey
- Roof Repair New Jersey
- Roof Replacement New Jersey
- Roof Leak Repair New Jersey
Related new resources in these production batches
Related roof-leak and roof-replacement resources
Frequently asked questions
Does this information guarantee that my claim will be covered?
No. Roof condition and contractor scope can be documented, but the insurance company applies the policy and makes the coverage decision.
What records help support a roof insurance claim?
Keep dated photographs, inspection notes, temporary-repair invoices, contractor measurements, estimates, claim correspondence, and proof of completed work.
Can Terra Nova interpret my insurance policy?
Terra Nova can explain roofing conditions and scope. Policy interpretation should come from the insurer, a licensed public adjuster where permitted, or qualified legal counsel.
Should emergency work wait for the adjuster?
Protecting people and preventing additional damage may be necessary before an inspection. Use reasonable temporary measures, photograph conditions, and keep receipts.
Why can the contractor estimate differ from the insurer estimate?
Measurements, quantities, repair boundaries, pricing databases, material availability, and concealed conditions can differ. Compare the documents line by line.
What should I do before signing a roofing contract?
Verify the contractor, read payment and cancellation terms, confirm the scope, understand how claim funds will be handled, and keep all promises in writing.
Last reviewed by Terra Nova Construction & Roofing: July 15, 2026. This page provides general educational information. Property conditions, policy coverage, warranty terms, municipal requirements, and project scope vary.
Get a professional evaluation
Send the property address, known age, photographs, and a short description of the concern. Terra Nova can inspect the connected roof or drainage components and prepare a written North Jersey scope.